Tuesday, August 23, 2016

Great Deals for the "Budget Conscious"

There are some GREAT deals out there to be had and most of them on a daily basis.  Here are just a few:


Sonic Drive-In Logo
SONIC Happy Hour 1/2 price drinks from 2-5pm EVERY DAY.  My favorite is the Cherry Limeade with extra cherry and extra lime.  (I also like the Cherry Lime Slush.)

SONIC 1/2 price Shakes after 8 pm.  I like this one because UNLIKE MANY other chain restaurants, they use REAL ICE CREAM!  (It REALLY bothers me that so many Ice Cream treats are now "Frozen Dairy Desserts".  That means they are NOT Ice Cream.)


Popeyes Louisiana Kitchen®. Fried Chicken, Chicken Tenders, Seafood & more! Visit one of our many fried chicken restaurants today.Popeye's Louisiana Kitchen in Herriman ONLY:  Thursday Night ONLY from 5-8pm, children's meals only 99¢.  They also do face painting, and a few other fun things.  They also usually have a pretty good "Special" for adults for about $4 or $5.


Taco Bell.  "Happier Hour" between 2-5pm, $1 small freeze drinks, or regular drinks.  I like the Baja Blast. But the Starbust flavored freezes are really good. and the Orange Vanilla Crush looks pretty good, but I haven't tried it yet.


Right now if you apply for a FREE Maverik Adventure Club Card at ANY location, you can get an XL soda for $1.  ANY DAY, ANY TIME, ANY LOCATION.

If you're a SODA freak, this is nice if you are out and about all day.


Culver's has about 8 or 9 "SnackPak" Meal Deals, all for around $5.  They include a small drink and small fries, but it is a complete meal for me, and their BURGERS (Called BUTTERBURGERS) are the best Fast Food Burgers money can buy.  If you've never had a butterburger, may I suggest giving them a whirl.
They also have "Kids Meals" ALL of which INCLUDE a kids size Frozen Custard.
Also, check the "Flavor of the Day" for the location nearest you, and plan your visits according to your favorite flavors.  My families favorite flavor is "Just Drummy."  But there are SO MANY GREAT FLAVORS...  Turtle, Double Marshmallow Oreo, Chocolate Oreo Volcano, Cherry Chocolate Chip, Caramel Cashew.

And here is a little known tip about the "Flavor of the day."  For Kids size, you can add 1 extra "Mix-In", and for larger sizes, you can ADD 2 ADDITIONAL "Mix-Ins." at no additional charge!  So my suggestion is to get the "Flavor of the Day" with 2 "Mix-Ins." when you go.


As I find more deals I will post them.  I will also try to keep this as up to date as possible.  Happy eating, drinking and snacking!

HELOCs may cause another rise in Foreclosures, Bankruptcies, and Short Sales.

Here is the latest information I have been distributing in our neighborhood.  This is GREAT information.  There is an old saying that says something to the effect of:
"Those that cannot remember the past are condemned to repeat it."  I believe it was Winston Churchill that gave us that great quote.

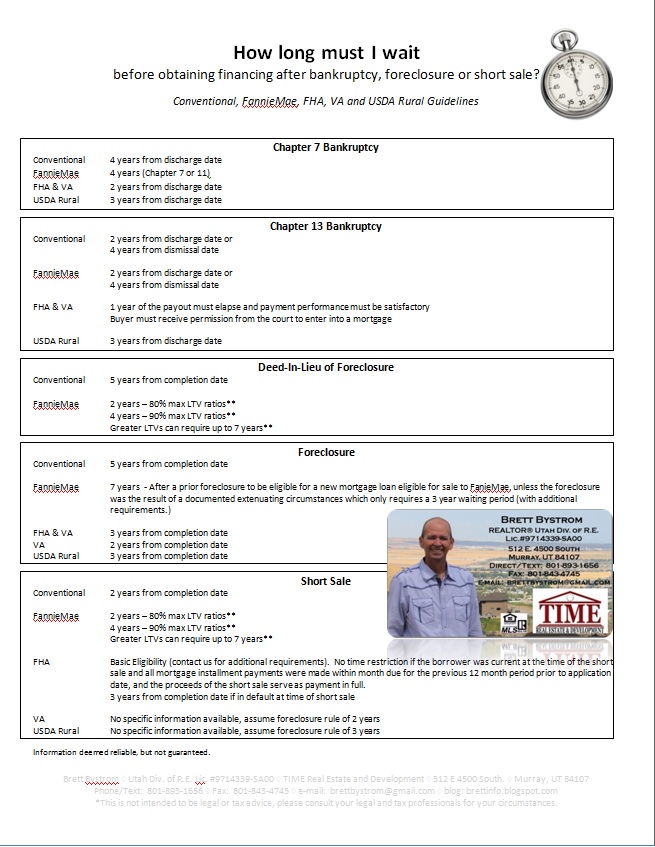
This attached flyer goes along great with that saying as it was only back in 2006-2008 that we had a FLOOD of property foreclosures, bankruptcies, and short sales in the housing market.  There were serious repercussions throughout the whole country.

This information is GREAT for those that may still be "feeling the burn" from 2006-2008, and may not know that they may be able to qualify for a home loan since that time. It also spells out the current thought in the industry, and that is; the HELOCs may cause the same scenario, but most likely not to the degree that 2006-2008 gave us.  However, if you know ANYONE that may be in danger of the attached scenario, please give me a call, I can go through every situation on a case by case basis.

Please feel free to share this blog with anyone that you think may benefit from it:
brettinfo.blogspot.com

Here is the flyer. (2 pages)


Friday, February 19, 2016

Real Estate Math

OK, so if you know me, you know I've always been somewhat of a math nerd...  I love math!  It makes sense, it doesn't change, there is a right and a wrong answer, and sometimes there are many different ways to come up with the right answer.

There are so many different things you need to be able to calculate in math to be a successful agent.

Simple interest, be able to calculate a monthly payment, calculate the ROI, or the capitalization rate, are just a few of the things an agent needs to be able to do.  Fortunately, this is a pleasure for me.  With a background in Financial Analysis at one of the largest mortgage bankers, my division was able to assist them in producing an average of $445 Million per month loan production, with a HIGH month of about $550 Million. 

The best thing about Real Estate, is that you have many backups.  You have lenders, and loan officers that will confirm your numbers, and even be able to give better estimates and more accurate market interest rates and monthly payments.  You also have escrow and title companies that confirm these numbers as well.  That's not to say that mistakes NEVER happen.  They do occasionally occur, so it is up to the agent and the borrower to confirm all numbers and verify their accuracy.

Utah Real Estate Acts, and their importance

There are a few acts relevant in Utah:

The Uniform Land Sales Practices Act
  Requires all Developers to register their projects with the Division of Real Estate.

The Timeshare and Camp Resort Act
  Requires all Timeshare developers/sales to disclose important facts and data about their projects, including Contact Information, Criminal Background Information, Project information and maximum number of interests available.

The Utah Marketable Record Title Act and Homestead Act
  Allows defects on title more than 40 years to be disregarded for marketable title.  And the Homestead Act protects the homeowner in the case of bankruptcy.

Thursday, February 18, 2016

Why is Equal Credit Opportunity so important?

The Equal Credit Opportunity Act is very important to create and maintain a level playing field for obtaining and accessing credit, whether it be for a mortgage for a home, or a credit card, or an auto loan, or any banking type loan.

It protects the following classes:

Race
Sex
Color
National Origin
Marital Status
Religion
And if they are receiving public assistance

A lender CAN use: history of credit, bankruptcies, foreclosures, judgments, credit score, etc. in determining credit worthiness.

Why is Fair Housing important?

The Fair Housing Act was passed in 1968 and enforced law that would make it illegal to discriminate against anyone based on:

1.  Race
2.  Color
3.  National Origin
4.  Sex
5.  Familial Status
6.  Religion
7.  Disability

If you believe you have been discriminated against, while trying to purchase or rent a home based on any of the above protected classes, you are encouraged to contact HUD.gov and report it.  I have been actively involved in the Equal Housing from my first day in the Mortgage and Real Estate Industry.  It is very important that every agent/broker knows and is sensitive to the public, and dealing with the public.  If you own real estate, it is your duty to educate anyone involved with dealing with the public, from leasing to maintenance.  They need to know how to interact properly with the people who lease property on your premises.

There ARE exemptions from this:
1.  When certain conditions are met, owners of single family homes are exempt when selling the home without the use of an agent and broker, so long as they are not discriminatory in advertising.
2.  The leasing of residential space of a 1-4 unit building, so long as the parties are not discriminatory in advertising and one of the units is owner occupied.
3.  Facilities owned by private and religious organizations may be leased to members for non-commercial purposes.

And this is NOT to be confused with denying rent for legitimate reasons:
Inadequate Credit
Inadequate Income
Misleading or False information given on the rental application
A negative rental rating
Or it may be that another rental applicant was just BETTER qualified.

If you contact HUD because of any of the above reasons, or conditions under the exemptions, they will most likely not be able to assist you.

Wednesday, February 17, 2016

What is a Deed?

There are actually MANY different kinds of deeds.

For the most part when you go to sell your home, the escrow company will have a Grant Deed drawn up, and you will execute the Grant Deed in front of a Notary Public.

The other types of deeds are as follows:

General Warranty Deed:  Guarantees that nobody has any claim to the property.  This is the best type of warranty.
Special Warranty Deed:  Says they have had no problem with the property for as long as they've owned the property.  These are better than quitclaim deeds, but not as secure as a General Warranty Deed.
Quitclaim Deeds:  Basically releases any and all interest in the property. No warranty is implied.
Contract for Deeds:  Used in Seller Financing.  Can get messy if the original owner has a mortgage, and they end up not paying on the mortgage after they sold it with seller financing.

And then there are the following:

Sheriff's Deed and Tax Deed - These types of deeds are the results of the owner defaulting either on the mortgage payment resulting in a sheriff's sale or defaulting on property taxes resulting in a tax sale.
Administrator's Deed - Used to transfer a property when an owner dies without a will.
Executor's Deed - Used when a person dies with a will to transfer the property.
Deed of Gift - Used when the property is transferred as a gift.

What is Title Insurance and why is it important?

If you have ever purchased a home, you see all kinds of fees, one of the fees you will always see if you are purchasing a home and are using conventional financing is a Title Insurance Fee.  There is a state maximum fee based on the purchase price of the home for all title insurance policies, so the fear that you are being charged too much for escrow and title is not likely at all.

So what is this Title Insurance?  It is basically an insurance product required by most lenders and protects THE LENDER against any deficiencies in title.  If there are any problems that come up down the road, the title policy would protect you and the lender against any claims on the property.  So a title insurance policy is a great way to protect yourself in case someone claims they own the property after you close escrow.

Tuesday, February 16, 2016

What if there is a mistake on the Closing Disclosure?

With the new disclosures since Dodd-Frank, there is now a mandatory closing disclosure to be given to the buyer and seller at least 3 days before closing.  What if you see that you are being charged for something you already paid for?  What if you see a mistake on the disclosure?

Great news!  since it's 3 days before closing, you have time to call your escrow/closing agent and let them know what you have found, then they can compare it with their information and have time to correct the document, and make sure all the funds go to the correct places to close escrow.  Most escrow agents are VERY easy to work with, and they realize they are in a position of service.  They are there to help you, so the good ones will take the time to make sure you are 100% satisfied.  There are MANY moving parts when buying or selling a home.  To think that you can do it all yourself is silly!  With Title, Escrow, Appraisal, Lending, Home Inspection, Pest Inspection...  you really think you can do it all yourself?  You need to find someone that can assist you, someone you trust, and someone with a track record of success.  There ARE good agents out there... and unfortunately, there are BAD agents out there... don't get stuck with one of the bad ones.

After the Mortgage Meltdown of 2007-2008, what is the next big fraud on the horizon?

The next big FRAUD ALERT on everyone's radar is the mortgage closing table fraud.  At the end of the transaction, in many states there is a "closing table" that usually happens at the escrow company, title company, law office, or real estate broker's office. 

The type of fraud that has happened at the closing table is mostly identity theft.  Real Estate Agents/Brokers seem to be the major fraudsters here, taking unsuspecting clients identities, taking out huge mortgages, and then making the payments of the mortgage to hide their deed.

Real Estate Agents forging documents and creating straw buyers.

Creating a fake law firm has been done and the fraudsters got away with $27 Million before they were caught.

There are many more types of fraud still being committed.  But the best way to protect yourself is to do some research on ALL the service providers you use, and remember, you are not OBLIGATED to use any/all of the services suggested by your real estate agent or lender. You get to decide who you work with and what service providers you choose.

But remember, your Real Estate Agent is on your side, so choose wisely which Real Estate Agent represents you.

Monday, February 15, 2016

What can I expect to see when I get an appraisal of my home

If you are buying or selling a single family home, you will most likely see an appraisal that uses the Sales Comparison Approach.

This approach takes the subject property, then the appraiser will do a walk through just to see if there is any significant damage to the home, holes in the wall, missing appliances, started projects that have not been completed, square footage, etc.  Then they will take a few pictures, mostly of the outside of the structure and the street surrounding the structure.  Then they take all this information back to their office and then the REAL work begins.  They may take HOURS researching homes in the neighborhood of the subject property and find similar properties, both in Lot size and structure size, as well as year built, and whether or not they both have swimming pools, 3 car garages, etc.  Then based on the recently sold data in the neighborhood, they can assess any differences in lot size, structure size or any differences and add or subtract value to come up with an appraised value.

Why is an appraisal important?

An appraisal will ALWAYS be required if you are financing the property through a traditional lender.  The appraisal process is in place to verify the existence of the property, as well as get a general feel for how the property stacks up against other homes in the vicinity.  This protects the banks, as well as may protect the buyer from purchasing a home that may be WAY overpriced compared to other surrounding homes.  I have seen deals where the price is agreed upon between the buyer and seller, and then the appraisal comes in, and the value is $10,000 below what the buyer and seller agreed upon.  What happens then?  That is a great question...  There are a few things that CAN happen. 

First, the seller may lower the price by $10,000 to match the appraised value, because he knows that another appraiser will not be able to raise the value of the appraisal.  Also, the banks will only use the value of the appraisal for lending purposes (not take into account the fact that the buyer and seller agreed on a different price), and now the real estate agents have a fiduciary duty to disclose this to any future buyers/banks should this deal fall apart.

Second, the buyer and seller may agree on a negotiated price somewhere in the middle, BUT the buyer will have to come in with additional cash, because the banks will only value the property at the appraised price.  So, for example, if the buyer and seller originally agreed on a $400,000 sales price, but the appraised value comes in at $390,000, the banks will only lend on the $390,000 price.  So if the banks set up the financing at 80% LTV (Loan To Value), originally, the buyer was expecting to get a loan for $320,000.  And they would put as a down payment $80,000 (20% Down Payment.)  Well, when the appraisal comes in low, they negotiate to meet in the middle, so if they split the $10,000 appraised value down the middle, and meet at a sales price of $395,000, the bank will still only loan 80% of the APPRAISED VALUE of $390,000, or $312,000, but now the buyer will have to come in with an $83,000 down payment to make the deal work for everyone.

Sunday, February 14, 2016

Supply and Demand... in Real Estate

Does the principles of Supply and Demand work in Real Estate?

Yes!  Absolutely!  Sometimes to a lesser degree than say a box of doughnuts, but the principles are the same, and the effect is the same.  Let's look at a couple examples:

If there is a new employer in town that is hiring top level software security experts, don't they need homes to live in?  And what type of homes do you think a top level software security expert want to live in?  My guess is they would make pretty good money, and would want their families to live in nice homes, so either a builder would have to come in and build nice homes, or the number of homes available for this type of person may be somewhat scarce, which would drive up the price of homes in the area.  So the principle is the same, the demand would go up, so the supply may go up, but if not, then the prices go up even more.

Now it is also true that the interest rates play a big part in what home prices do as well.  If a buyer goes to his loan officer and gets pre-qualified for a home, typically, here in the U.S.A., the buyer wants to buy as big of a home as they can afford.  So if the interest rates are low, that will allow them to purchase a larger home, if the interest rates start going up, they may start looking at smaller homes.  Also, if the trend continues, and interest rates continue to rise before they are able to purchase a home, the price of homes may start to slip a little, and may even go down a little, however, that usually means their monthly payment will be the same, just more of their payment will go to interest.

Lastly, if an employer who employs thousands of workers in the area closes up shop, moves out of state, what happens to the housing prices in the area they left?  Yep, lots of homes for sale in the area, lots of competition to sell a house quickly means, usually, the savvy seller knows that to sell quickly, you have to make the price EXTRA attractive to potential buyers... that means lowering the price below market average, and if enough sellers want to sell quick enough, the price of homes can go down quickly.  Does this always happen?  No.  But can this happen?  Yes.  And that's how Supply and Demand can affect Real Estate.

Saturday, February 13, 2016

Home Warranty

There are many different Home Warranty companies out there.  Old Republic, American Home Shield, First American Home Warranty, etc.  They all do basically the same thing...  They insure the home's existing appliances, A/C, pool equipment, and some even have roof protection for an additional fee.  (Usually, A/C, and pool equipment are slightly more expensive to include as well.)  But, in most cases, if one of these breaks down during the first year of ownership, it typically will cost a $50-$75 service charge (or some companies call it a deductible) to repair or replace the defective unit.  And if they come out, and for some reason say the item is not covered (which DOES happen occasionally, when the home inspection calls out issues with the unit.), they still charge you the $50-$75. And then you still have to repair or replace the defective unit.

On the other hand, I have had clients receive brand new, upgraded dishwashers because the installed model was no longer available.  I have also had clients receive a new water heater because there was no sign that the installed one was going to die on them.  So in those cases, it makes perfect sense to pay $50 and get a new dishwasher, or water heater... installed.

Utah's State Construction Registry

In Utah, there are some potential issues for contractors, subcontractors, suppliers of building materials, and owners of the new construction project.

To help safeguard all involved, the state has created a mandatory online submission for everyone who owns/builds on/supplies for a property with a construction project.

The overall view is that if the owner pays the General Contractor, they hire a SubContractor, who gets their supplies from a local building supplier, the chain of who does what is fairly evident to the General Contractor, however, the owner doesn't necessarily know who is working on his house.  He only knows that he hired a General Contractor.  So if the General Contractor skips out, and leaves town without paying the SubContractor, who in turn would need to pay his supplier, especially after he was paid by the owner of the home, this presents a huge problem... the owner would essentially pay for some things twice in order to free all the liens on his property.  The State Construction Registry if properly used is supposed to address all these issues.

If everyone working on a project registers on the website, then the owner knows who did what, who provided what, and who needs to be paid for what.  Simple as that!

Friday, February 12, 2016

Beware of Foreclosure SCAMs

I think it is unfortunate that there are people in the world that take advantage of desperate people in desperate situations.  Think about it, someone has defaulted on their loan, they stand to lose their home, and then a fraudster comes in, says give me some money and I will fix it, however, they do absolutely nothing.  It's shameful!

The NUMBER 1 RULE when searching for someone to help you with mortgage relief is: Pay Nothing Up Front.  (That is the law.  Period.)  Under NO circumstances should you pay anyone to assist you with a loan modification or bail you out of your foreclosure.  There are "straw buyers" out there that basically artificially inflate the value of the property for appraisal purposes, then has their straw buyer buy the property, then they promise the borrower can buy the property back.  I don't know how anyone doesn't see "red flags" all over this scenario.  Well, if you don't, hopefully you will look for the warning signs.

Just remember, if something sounds too good to be true, it usually is.  Sorry to be a dream killer.  :-)

What is LTV and why is it important?

When qualifying for a loan, most lenders will look at the Loan To Value (LTV).  If a borrower is willing to put in money toward the purchase, this tells the lender that the borrower is not as likely to default on the loan.  Basically, the borrower has some "skin in the game."  Consequently, the lower the LTV, the more attractive the loan to a lender.

Conversely, a typical FHA loan is 96.5% LTV.  That means the borrower only needs to come in with 3.5% down payment in order to purchase the home.  This is why the FHA loan is so popular.  They have relaxed underwriting guidelines, HOWEVER, they ALL require MI (Mortgage Insurance.)  This mortgage insurance can be quite expensive, hundreds of dollars per month.  And the only use for this insurance is if YOU DEFAULT on the loan, and the only beneficiary is the lender in case of default.  Ideally, I recommend hat borrowers either come in with 20% down, and avoid the MI altogether, or occasionally, it makes sense to do a second lien that will avoid M.I.  As mentioned, it can be hundreds of dollars per month, so if the math works out, then it makes sense.  Any competent Loan Officer will be happy to run the numbers for you.  And if they won't, please... PLEASE contact me directly.  I will be happy to put you in touch with a lender that WILL do the math for you.

Best of luck!

How do I improve my credit score quickly?

This is one of my favorite questions.  There are many things one can do to improve their credit score, but the most important thing I can tell someone is to just not get in over their head.  Make sure that anything they put on credit, they absolutely NEED.  (Not just "want.")  And then make absolutely sure that you make the payments ON TIME EVERY MONTH.  If you can't commit to making the payment every month, it is probably NOT a good idea to purchase the item.  By simply doing this, your credit score will skyrocket.

However, there are those that have made some mistakes in the past.  If you do carry a balance, the easiest and quickest way to get a little boost in your credit score is to call your credit card company and ask for a credit limit increase.  This may sound a little strange, but the math works out like this...

If you carry a balance of $1500 on your credit card, and your credit limit is $2000, you have $500 of unused credit, or 25% of unused portion of your credit.  If you are able to call your credit card company and have them raise your credit limit to $3000, well, your balance is still only $1500, but your unused portion of your credit is now $1500, or 50% unused credit.  (You just have to make sure you don't go and max out the new unused portion of your credit.

Some of the things that seem like they would help your credit score, actually can drag down your score.  For instance, if you have older collections, it seems like you would want to pay them off before applying for a new loan.  However, there are instances when it will actually hurt you.  The reasoning is because it was an older collection and had not been reported on for months, maybe even years, but when you pay it off, it now shows as new, even though its paid off.

My personal recommendation is to NOT use credit once it's established.  However, the only way to get a credit score is to USE credit.  So for most people, I would recommend a small auto loan, and make sure you make the payment every month.  Then get a small credit card, maybe $500 limit, and purchase only necessities, then carry a very small balance every month, $250, this will show that you understand how to use credit.  Even if your APR is ridiculously high, at 25% and you carry a balance of $250, your monthly interest payment will only be $5.21/month ($250 x .25 / 12 months = $5.2083333)  I personally, would consider $5.21/month a good investment in your credit, and in your future as a homeowner.

What is a Bridge, Gap, or Swing loan?

If you own a property and have a significant amount of equity in the property, there are private money lenders out there that have cash on hand, and want to lend out money.  These lenders have been tightly regulated over the past few years, however, the interest rates are still significantly higher, and these lenders are much more proficient at foreclosing on your property if any payments are missed. 

Occasionally, there may be a rare opportunity when I would recommend one of these Hard Money loans (Also called Bridge, Gap, or Swing loans), but for the most part I would not recommend this type of loan.  One of the rare situations would be, if you find the perfect property at an unbelievable price, and the seller has only given you about a week to get the money together to buy the property.  How often has this situation come up in your life?  If you said, "Never." don't worry, I haven't ever come across it either... and I'm in the industry.

The reality is, these loans are far too expensive unless you have money to burn.  I highly recommend skipping this option, and if you need to sell a property to buy another one, give me a call, I have ways of protecting you from being "kicked out" of your home during the whole process of selling your home and buying a new home.

No matter where you are in the U.S.  I have GREAT contacts ALL over the country!  Give me a call/text, I can definitely help!

Thursday, February 11, 2016

What is the difference between a Fixed Rate Mortgage and an Adjustable Rate Mortgage?

There are many different types of home financing loan programs, but for most Americans that just want to make their monthly payments and own their home one day, the 30 Year Fixed Rate Home Mortgage is the best option.

This is the best option because it gives them the lowest possible payment every month, and the payment will not change over the life of the loan.  The Amortization is the same as the loan, 30 years, or "Fully Amortized."  These are widely available loans and they typically have the broadest underwriting guidelines available to most borrowers.

The next few types of loans are typically only used in special circumstances.

Interest Only ARM loans (Adjustable Rate Mortgage):  In rapidly appreciating areas, these are a great option to "get your foot in the door", have a manageable payment every month, and then the goal is to refinance into a 15 or 30 year fixed loan, once you have been able to get rid of the M.I. (Mortgage Insurance.)  This has been typically at 80% LTV (Loan To Value) however, recent changes to the M.I. schedules may require you to refinance to take advantage of removing the M.I.  Please make sure you discuss with your loan officer about removing the M.I.  These loans also have "caps" associated with the adjustable terms.  The caps are typically 2%/2%/6%.  (That is, 2% initial maximum jump from the original rate, 2% maximum jump every adjustment term, with a maximum of 6% increase cap over the initial rate for the life of the loan.)

Fully Amortized ARM loans:  Very similar usage to the Interest Only ARM Loans above.  The difference is that Interest AND Principal are due each month.

Neg-Am Loans:  (Negative Amortization Loans, Sometimes these are also called PayOption ARM loans):  The lender actually gives you 4 options to pay each month, but what was not crystal clear to the average borrower was that if you chose the cheapest payment every month, true, it would not hurt your credit score, however, you would not even be covering all of the interest due each month, so they would "tack on" the interest to your principal balance at the end of the loan term.  OUCH!  This loan has traditionally been reserved for ONLY the most savvy investor who understands about cash flow.  Mostly commercial real estate developers, who plan on selling in the near future, and are just streamlining their cash flow for the short term.  This may be the "straw that broke the camel's back" with the mortgage meltdown in 2007 - 2008. 

Subprime Loans:  These are typically higher interest rate loans, and either 2/28 or 3/27.  And most of them have a PrePayment Penalty built into them (unless not allowed by state law.)  These were meant to be a "band aid" loan, typically to get a borrower into their home, or refinance their home with this loan, then work on repairing their credit, then refinance into something more traditional.  This is the loan program that got all the blame for the mortgage meltdown of 2007-2008.  And while there was definitely some abuse of these types of loans, the FINAL straw was the Pay-Option ARMs.